FINANCIAL LITERACY | SELF-EMPOWERMENT | TAX YEAR 2026
From Minimum Wage to Six Figures: What Your Paycheck Really Looks Like
Your first wage does not have to be your final wage. But as your income grows, your financial knowledge has to grow with it — and almost nobody explains what happens to the money in between.
By Dance Mogul Magazine | Financial Literacy | September 2026
WHAT THIS ARTICLE COVERS
The paycheck nobody explains · What a wage actually is · The first math lesson · Meet your paycheck · Social Security and Medicare · Salary is not taxable income · The tax-bracket staircase · The 2026 brackets · The income ladder · Where the credits come from · Real jobs at these salaries · The $100,000 centerpiece · Destroying the 22% myth · Same income, three households · Why you can still owe · Your W-4 · Should you fear a raise? · Six figures is not rich · Four money numbers · What grows with your salary · Total compensation · If you work for yourself · State and local taxes · Myth vs. reality · Professional help · Official resources · FAQ
The Paycheck Nobody Explains to You
If you get up, go to work, and earn money — you deserve respect. Full stop.
Maybe your first paycheck comes from a grocery store. A restaurant. A retail floor. An amusement park in the summer. A warehouse on an overnight shift. A front desk. A studio where you sweep the floor before class starts.
The dollar amount on that check does not determine the dignity of the work. Somebody has to do the job. You did it. You showed up on time, you followed instructions, you handled a customer who was having a bad day, and you got paid for it.
That is not a small thing. That is the beginning of something.
A first job teaches responsibility, punctuality, communication, teamwork, accountability, independence, and the relationship between your time and your income. Those lessons transfer to every job that comes after — including the ones that pay ten times more.
And here is the part that matters: your first wage does not have to be your final wage.
You can be grateful for today's opportunity and still decide you want something different tomorrow. You can appreciate the job that is feeding you right now and still set your sights on $30,000, then $50,000, then $75,000, then six figures. There is nothing wrong with ambition. Ambition is how people build lives.
But here is what almost nobody explains before that first paycheck arrives:
The number your employer promised you is not the number that reaches your bank account.
This article walks that entire journey — from a minimum-wage paycheck all the way up past six figures — and shows you exactly what happens to every dollar along the way. Not to discourage you from earning more. The opposite. The goal is to make sure your financial knowledge grows at the same speed your income does.
Because earning more money is an accomplishment. Understanding what happens to it is power.
First, What Is a Wage?
Let's start with nothing assumed.
Minimum wage is generally the lowest hourly amount an employer covered by a particular minimum-wage law can legally pay an employee, subject to exceptions.
The federal minimum wage is $7.25 per hour. It has been $7.25 since July 24, 2009.
But — and this matters enormously — $7.25 is not what every minimum-wage worker in America earns. Many states and cities have set their own minimum wages that are higher than the federal one. When federal and state minimum-wage laws both apply, the worker is generally entitled to the higher of the two. Some state minimums are more than double the federal figure.
So if you are working in a state with a higher minimum, your floor is higher. Check your own state's rules through the U.S. Department of Labor rather than assuming the federal number applies to you.
KNOW THE YOUTH MINIMUM WAGE
Federal law lets employers pay workers under 20 years old not less than $4.25 per hour during the first 90 consecutive calendar days after they are first employed.
Four things worth knowing if that is you: it is 90 calendar days, not 90 days of work, and the clock keeps running even if you take time off. The day you turn 20, your pay must rise to at least the applicable minimum wage even if the 90 days are not finished. Your employer cannot fire, cut the hours of, or reduce the benefits of an existing employee in order to hire someone at the youth wage — that is illegal displacement under the Fair Labor Standards Act. And where state or local law requires a higher minimum with no under-20 exception, the higher standard applies.
Know your own rules. Knowing them is part of protecting yourself.
The First Math Lesson
Let's use the federal minimum wage as a teaching example.
| Step | Math | Result |
|---|---|---|
| Hourly rate | Federal minimum wage | $7.25 |
| One week | $7.25 × 40 hours | $290 |
| One year | $290 × 52 weeks | $15,080 |
Now here is the first real lesson of this entire article:
$15,080 IS GROSS EARNINGS. IT IS NOT $15,080 IN YOUR BANK ACCOUNT.
The distance between those two numbers is what the rest of this article is about.
Meet Your Paycheck
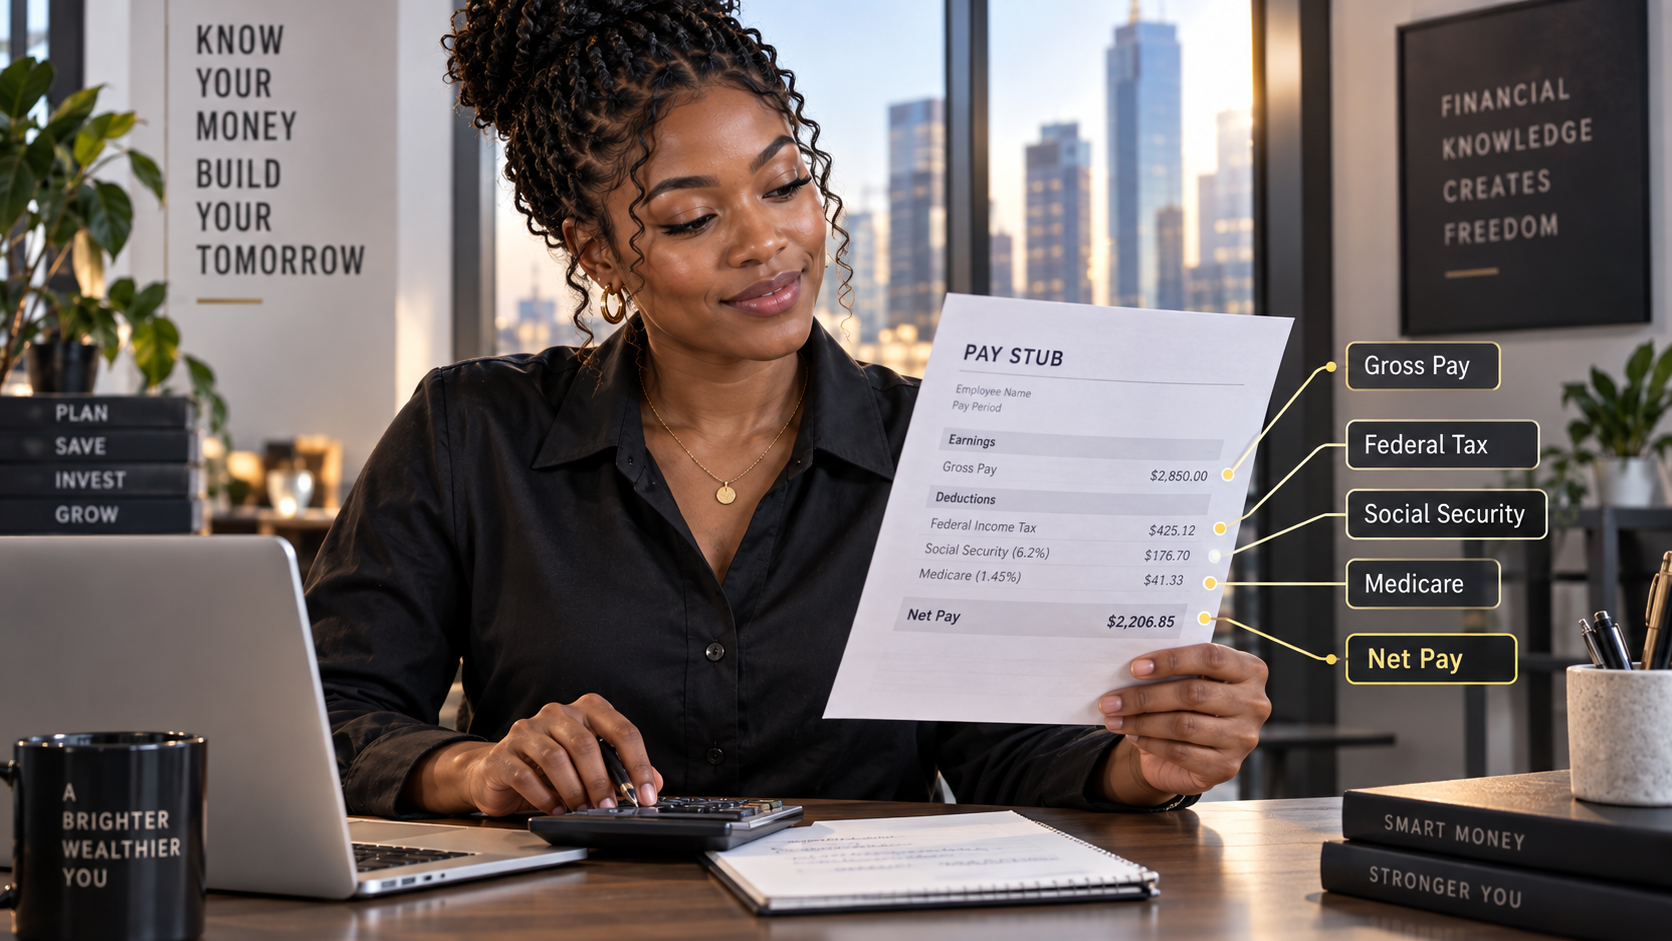
Four words. Learn them now and the rest gets easier.
| Term | What it means |
|---|---|
| Gross Pay | The amount you earned before anything is taken out. |
| Deductions | Amounts removed for taxes, insurance, retirement or other items. |
| Net Pay | What is left after deductions. |
| Take-Home Pay | The amount that actually reaches you. |
Money flows through your paycheck in roughly this order:
GROSS PAY → PAYROLL TAXES → FEDERAL INCOME-TAX WITHHOLDING → STATE / LOCAL TAXES WHERE APPLICABLE → BENEFITS, RETIREMENT AND OTHER DEDUCTIONS → TAKE-HOME PAY
The single most common mistake people make when reading a pay stub is assuming everything removed is “income tax.” It is not. Some of it is something else entirely — and that something else is where we go next.
Social Security and Medicare: The Taxes That Aren't Income Tax
Look at your pay stub and you will find lines that have nothing to do with income tax. For most employees these are payroll taxes, often labeled FICA.
| Payroll tax | Employee rate | Applies to |
|---|---|---|
| Social Security | 6.2% | Wages up to $184,500 in 2026 |
| Medicare | 1.45% | Every dollar of covered wages, no cap |
| Combined FICA | 7.65% | From your very first paycheck |
| Additional Medicare | 0.9% | Wages over $200,000 single and head of household, $250,000 joint, $125,000 married filing separately |
Your employer pays a matching 6.2% and 1.45% that you never see on your stub. There is no employer match on the Additional Medicare Tax, and its thresholds are written into law rather than adjusted for inflation — which means more people cross them every year as wages rise.
SOCIAL SECURITY AND MEDICARE TAXES ARE SEPARATE FROM FEDERAL INCOME TAX.
This is why our minimum-wage worker matters as an example. At $15,080, a single filer with no children owes $0 in federal income tax — the standard deduction is larger than their entire income. But they still pay $934.96 in Social Security and $218.66 in Medicare, for $1,153.62 in federal payroll tax.
Zero income tax. Still $1,153.62 gone. If nobody had ever explained payroll taxes to that worker, their first pay stub would be genuinely confusing.
Salary Is Not the Same Thing as Taxable Income
This is one of the most important turns in the whole article, so read it twice.
When someone says “I make $100,000,” people assume the government applies tax rates directly to that $100,000.
It does not work that way.
Income moves through stages, and the tax rates apply to the last number, not the first:
GROSS INCOME → MINUS ADJUSTMENTS AND DEDUCTIONS → TAXABLE INCOME → TAX RATES APPLY HERE
For most people the biggest single reduction is the standard deduction — a flat amount you subtract from your income without having to document anything. For tax year 2026:
| Filing status | 2026 standard deduction |
|---|---|
| Single | $16,100 |
| Married Filing Jointly | $32,200 |
| Head of Household | $24,150 |
So a single person earning $100,000 does not have $100,000 of taxable income. They have $100,000 − $16,100 = $83,900.
That $16,100 gap is real money, and it is invisible to anyone who only looks at their salary.
The Tax-Bracket Staircase
Now the part almost everyone gets wrong.
For 2026 the federal ordinary income-tax rates are:
10% → 12% → 22% → 24% → 32% → 35% → 37%
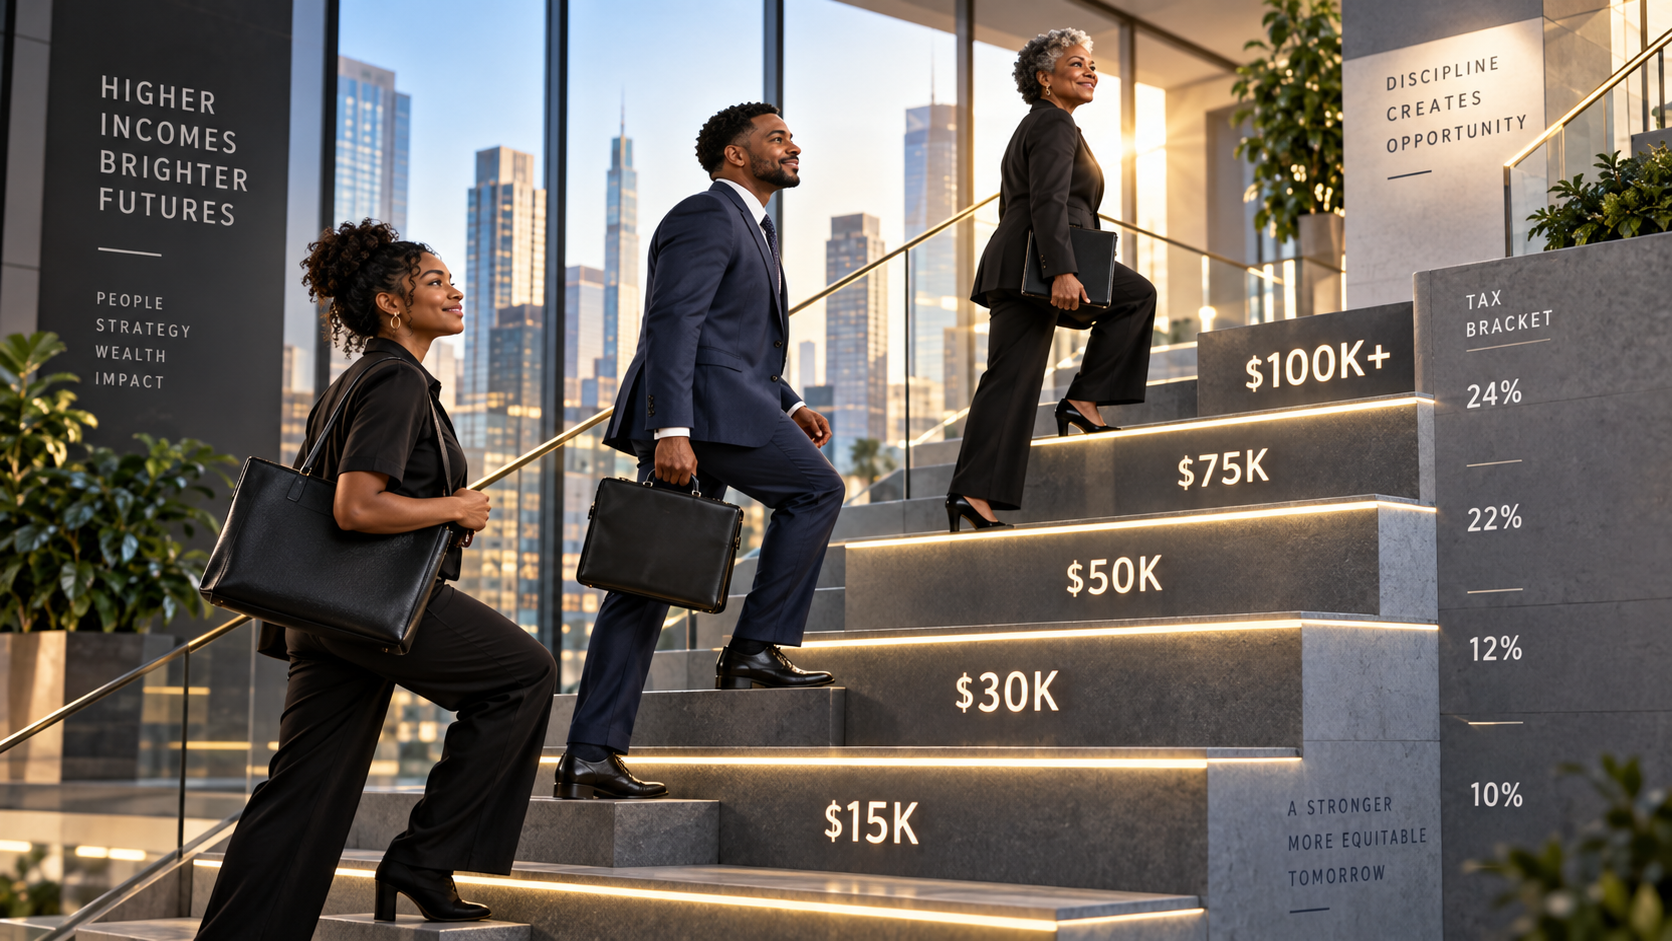
Picture a staircase. Or better, picture a row of buckets lined up, each a different size.
Your taxable income gets poured into the first bucket. When that bucket fills, the overflow goes into the second bucket. When that fills, the overflow goes into the third. And so on.
Each bucket is taxed at its own rate. The dollars already sitting in the earlier buckets do not climb back out and get re-taxed at the new rate.
GETTING A RAISE INTO THE NEXT TAX BRACKET DOES NOT MAKE ALL OF YOUR INCOME SUBJECT TO THAT HIGHER RATE.
Read that again. It is the single most expensive misunderstanding in personal finance, because it causes people to turn down promotions, refuse overtime, and fear raises that would have left them better off.
Two terms come out of this, and they are worth learning properly:
- Marginal tax rate — the rate that applies to your next taxable dollars, inside your highest occupied bracket. It is the rate on the edge of your income.
- Effective tax rate — your total federal income tax divided by the income measure being discussed. It is the average across all your dollars.
Your effective rate is always lower than your marginal rate, as long as you have income in more than one bracket. Always.
ONE CAUTION MOST ARTICLES SKIP
When someone quotes an effective tax rate, ask what they divided by. Dividing tax by gross income gives one number. Dividing by taxable income gives a higher number. Both can be correct — they answer different questions. We show you both.
The 2026 Federal Income-Tax Brackets
These are the official 2026 rate schedules. Every calculation in this article was built from this table, computed twice by two different methods, and reconciled before publication.
Single
| Rate | Taxable income |
|---|---|
| 10% | $0 – $12,400 |
| 12% | $12,400 – $50,400 |
| 22% | $50,400 – $105,700 |
| 24% | $105,700 – $201,775 |
| 32% | $201,775 – $256,225 |
| 35% | $256,225 – $640,600 |
| 37% | Over $640,600 |
Head of Household
| Rate | Taxable income |
|---|---|
| 10% | $0 – $17,700 |
| 12% | $17,700 – $67,450 |
| 22% | $67,450 – $105,700 |
| 24% | $105,700 – $201,750 |
| 32% | $201,750 – $256,200 |
| 35% | $256,200 – $640,600 |
| 37% | Over $640,600 |
Married Filing Jointly
| Rate | Taxable income |
|---|---|
| 10% | $0 – $24,800 |
| 12% | $24,800 – $100,800 |
| 22% | $100,800 – $211,400 |
| 24% | $211,400 – $403,550 |
| 32% | $403,550 – $512,450 |
| 35% | $512,450 – $768,700 |
| 37% | Over $768,700 |
READ THE TABLE CORRECTLY
These are taxable-income figures, not salary figures. A single person does not reach the 22% bracket at a $50,400 salary. They reach it at roughly a $66,500 salary, because the standard deduction shields the first $16,100.
The Income Ladder
Here is the centerpiece. Nine income levels, three households, all federal, all 2026.
- Person A is single with no children.
- Person B is a parent with one qualifying child who legitimately qualifies for Head of Household status.
- Person C is a married couple filing jointly, and the figure shown is combined household income.
| Annual income | Single | HoH + 1 child | Married (combined) |
|---|---|---|---|
| $15,080 | $13,926 | $20,053 | $13,926 |
| $30,000 | $26,285 | $32,771 | $27,705 |
| $50,000 | $42,355 | $45,882 | $44,395 |
| $75,000 | $61,593 | $65,715 | $64,623 |
| $100,000 | $79,180 | $84,962 | $84,710 |
| $150,000 | $113,791 | $119,734 | $123,185 |
| $250,000 | $183,182 | $187,567 | $197,468 |
| $500,000 | $340,477 | $345,103 | $376,453 |
| $750,000 | $495,236 | $500,023 | $534,418 |
Each figure is estimated income remaining after modeled federal income tax and employee payroll taxes, before state and local taxes and other deductions. Source: IRS Rev. Proc. 2025-32; SSA 2026 COLA fact sheet. Calculated and independently re-verified by Dance Mogul Magazine.
Two of those numbers should stop you.
At $15,080, the Head of Household parent ends the year with more money than they earned — $20,053 against $15,080 of wages. That is not an error. Refundable credits, which we explain below, can exceed a person's tax bill and produce a payment.
At $30,000, the same thing happens again: $32,771 remaining on $30,000 of income.
Meanwhile Person A at $15,080 ends with $13,926 — less than they earned, because payroll taxes come out regardless.
SAME COUNTRY. SAME TAX CODE. SAME YEAR. WILDLY DIFFERENT RESULTS, BECAUSE HOUSEHOLD CIRCUMSTANCES DIFFER.
Where the Credits Come From
Two federal credits drive most of the difference in that table, and both come with real eligibility rules that we are not going to gloss over.
The Child Tax Credit
For 2026 the maximum Child Tax Credit is $2,200 per qualifying child. Up to $1,700 per child can be refundable through the Additional Child Tax Credit, generally calculated as 15% of earned income above $2,500, capped at $1,700 per child.
To claim it, the child must generally:
- Be under 17 at the end of the tax year
- Be related to you in a qualifying way
- Live with you for more than half the year
- Not provide more than half of their own support
- Be claimed as a dependent on your return
On top of that, you — and your spouse, if filing jointly — and each qualifying child must have a Social Security number valid for employment, issued before the return's due date including extensions. The credit begins to phase out above $200,000 of income ($400,000 for joint filers).
No parent automatically receives the full credit. Every one of those tests has to be met.
The Earned Income Tax Credit
The EITC is a refundable credit for working people with low to moderate income. For 2026, a taxpayer with one qualifying child can receive a maximum of $4,427, phasing out completely at $51,593 for single and head of household filers. With no children, the maximum is far smaller — $664.
THE RULE THAT MATTERS MOST TO A TEENAGER
To claim the EITC with no qualifying children, you generally must be at least 25 and under 65. A 17-year-old working a summer job does not qualify for it.
That is exactly why the “Single” column in our ladder does not include the EITC — including it would have misrepresented the reader we are writing for. There is also an investment income limit of $12,200 for 2026.
Credits are powerful. They are also conditional. Never assume one applies to you without checking the rules.
What These Salaries Look Like in Real Jobs
Numbers on a page are abstract. Here is roughly where these income levels live in the working world, using national wage data from the U.S. Bureau of Labor Statistics (May 2025 estimates, the most recent available).
| Income level | Occupations that can land near here | BLS annual mean |
|---|---|---|
| ~$32,000–$37,000 | Fast food and counter workers; cashiers; retail salespersons | $32,150 / $33,180 / $37,310 |
| ~$40,000–$47,000 | Stockers and order fillers; laborers and material movers; office clerks; customer service representatives | $39,540 / $42,260 / $46,420 / $46,590 |
| ~$70,000 | All occupations, national average | $69,770 |
| ~$100,000 | Registered nurses | $101,420 |
| ~$135,000 | General and operations managers | $134,940 |
U.S. Bureau of Labor Statistics, Occupational Employment and Wage Statistics, May 2025 (released May 2026). Figures are national annual mean wages.
A profession does not automatically pay the number next to it. Actual pay varies by geography, experience, education, specialty, employer, industry, hours worked, union status, bonuses, commissions, self-employment, and market conditions. Two registered nurses in two different states can earn very different amounts. These figures are illustrative — use the BLS occupational data for your own field and your own metro area before making a plan around a number.
One figure deserves attention on its own: the national annual mean wage across all occupations was $69,770. That is useful context for what “six figures” actually represents in the broader American workforce.
“I Finally Make $100,000. Now What?”
Six figures is the number people dream about. It shows up in songs, in goals written on bathroom mirrors, in the thing you tell yourself you'll hit by thirty.
So let's take it apart completely.
| Step | Amount |
|---|---|
| Gross salary | $100,000.00 |
| Less standard deduction | − $16,100.00 |
| Taxable income | $83,900.00 |
| First $12,400 taxed at 10% | $1,240.00 |
| Next $38,000 taxed at 12% | $4,560.00 |
| Remaining $33,500 taxed at 22% | $7,370.00 |
| Federal income tax | $13,170.00 |
| Social Security (6.2% of $100,000) | $6,200.00 |
| Medicare (1.45% of $100,000) | $1,450.00 |
| Employee payroll taxes | $7,650.00 |
| Total modeled federal tax | $20,820.00 |
| Estimated remaining income | $79,180.00 |
That last line is estimated income remaining after modeled federal income and employee payroll taxes, before state and local taxes and other deductions. It is deliberately not called “take-home pay,” because health insurance premiums, retirement contributions, and state and local taxes have not been subtracted yet. Your actual deposit will be lower.
Spread across the year, the $100,000 salary looks like this:
| Period | Gross | Remaining after modeled federal tax |
|---|---|---|
| Annual | $100,000.00 | $79,180.00 |
| Monthly | $8,333.33 | $6,598.33 |
| Biweekly (26 checks) | $3,846.15 | $3,045.38 |
| Weekly | $1,923.08 | $1,522.69 |
Destroying the 22% Myth
Now use that example to kill the most common tax misconception in America.
Someone earning $100,000 looks up the brackets, sees that they land in the 22% bracket, and concludes:
“I'm in the 22% bracket, so the government takes $22,000 of my $100,000 in federal income tax.”
The actual federal income tax was $13,170.
The myth overstates it by $8,830 — nearly nine thousand dollars of imaginary tax.
Here is why. The 22% rate applied to only $33,500 of that person's income. The dollars below that were taxed at 12%, and the dollars below those were taxed at 10%, and the first $16,100 was not taxed at all because the standard deduction removed it.
| Which rate? | Value | What it measures |
|---|---|---|
| Marginal rate | 22% | The rate on the next dollar earned |
| Effective rate on taxable income | 15.70% | Total tax ÷ $83,900 |
| Effective rate on gross salary | 13.17% | Total tax ÷ $100,000 |
Three different, all-correct percentages for the same person in the same year. When someone quotes you a tax rate, find out which one they mean.
The Same $100,000, Three Different Households
Now watch what happens when we hold income perfectly still and change only the household.
| Single | HoH + 1 child | Married Filing Jointly | |
|---|---|---|---|
| Gross income | $100,000 | $100,000 | $100,000 (combined) |
| Standard deduction | $16,100 | $24,150 | $32,200 |
| Taxable income | $83,900 | $75,850 | $67,800 |
| Income tax before credits | $13,170 | $9,588 | $7,640 |
| Child Tax Credit applied | — | − $2,200 | — |
| Net federal income tax | $13,170 | $7,388 | $7,640 |
| Employee payroll taxes | $7,650 | $7,650 | $7,650 |
| Total modeled federal tax | $20,820 | $15,038 | $15,290 |
| Estimated remaining income | $79,180 | $84,962 | $84,710 |
| Marginal rate | 22% | 22% | 12% |
| Effective rate on gross | 13.17% | 7.39% | 7.64% |
The single filer pays $5,782 more in federal income tax than the parent, and $5,530 more than the married couple — on identical income.
TWO PEOPLE CAN EARN THE SAME AMOUNT OF MONEY AND HAVE COMPLETELY DIFFERENT TAX OUTCOMES.
Salary alone does not determine what you owe. Filing status, household composition, deductions, and credits all move the number. This is also why comparing your tax bill to a coworker's rarely tells you anything useful — you are probably not running the same return.
HEAD OF HOUSEHOLD IS NOT AUTOMATIC
It is frequently claimed incorrectly. You must meet all three tests: you are unmarried, or considered unmarried, on the last day of the year; you paid more than half the cost of keeping up your home for the year; and a qualifying person generally lived with you for more than half the year.
Not every unmarried parent qualifies. The IRS treats improper Head of Household claims seriously.
Why Someone Can Make $100,000 and Still Owe the IRS
High income does not automatically create a balance due. What creates a balance due is a mismatch.
For employees, federal income tax is withheld from every paycheck throughout the year. At filing time, you reconcile two numbers: what you actually owed, against what was already withheld and paid.
| If withholding was… | Result |
|---|---|
| More than you owed | Refund |
| About right | Small refund or small balance |
| Less than you owed | Balance due, and potentially penalties |
A TAX REFUND IS GENERALLY NOT FREE MONEY FROM THE GOVERNMENT.
In most common situations, a refund is money that was already taken out of your earnings during the year, beyond what your final liability required. You are getting your own money back. Refundable credits like the EITC and the Additional Child Tax Credit can also create or increase a refund — that part genuinely is additional money, not a return of your own withholding.
A REAL MECHANISM THAT CATCHES PEOPLE OFF GUARD
Consider a married couple with $300,000 in combined wages, each spouse earning $150,000 at a different employer. Employers must withhold the 0.9% Additional Medicare Tax only once an individual employee's wages pass $200,000 with that employer.
Neither spouse crossed $200,000 at their own job, so neither employer withheld any of it. But the couple's combined wages exceed the $250,000 joint threshold, so $450 is genuinely owed — and it gets settled on the return.
Nobody did anything wrong. The withholding system simply cannot see the whole household from inside one payroll department. That is what the W-4 is for.
Your W-4 Is a Steering Wheel
Employees generally use Form W-4 to give their employer the information used to determine federal income-tax withholding. It is not a one-time form you fill out on day one and forget. It is an adjustment you can make whenever your situation changes.
Life events that can change what your withholding should be:
- Marriage or divorce
- A new child
- Taking a second job
- A spouse starting or stopping work
- A significant raise
- Bonus income
- Starting a side business
- Investment income
The IRS publishes a free Tax Withholding Estimator at irs.gov, built for exactly this. Run it after any of the events above.
What this article will not do is tell you what to enter on your W-4. That depends on your complete financial picture, and this is general education, not individualized tax advice.
Should You Be Afraid of a Raise?
Let's answer the question directly with real numbers.
Scenario 1: $95,000 to $110,000, single filer
| Before | After | |
|---|---|---|
| Salary | $95,000 | $110,000 |
| Taxable income | $78,900 | $93,900 |
| Marginal bracket | 22% | 22% |
| Total modeled federal tax | $19,338 | $23,785 |
| Estimated remaining income | $75,663 | $86,215 |
The $15,000 raise put $10,553 more in this worker's pocket — about 70% of it. And notice: this raise did not even change the marginal bracket. Taxable income moved from $78,900 to $93,900, and the 24% bracket does not begin until $105,700 of taxable income. A raise that feels like it should push you into new territory often does not.
Scenario 2: $118,000 to $130,000 — a raise that genuinely does cross a bracket
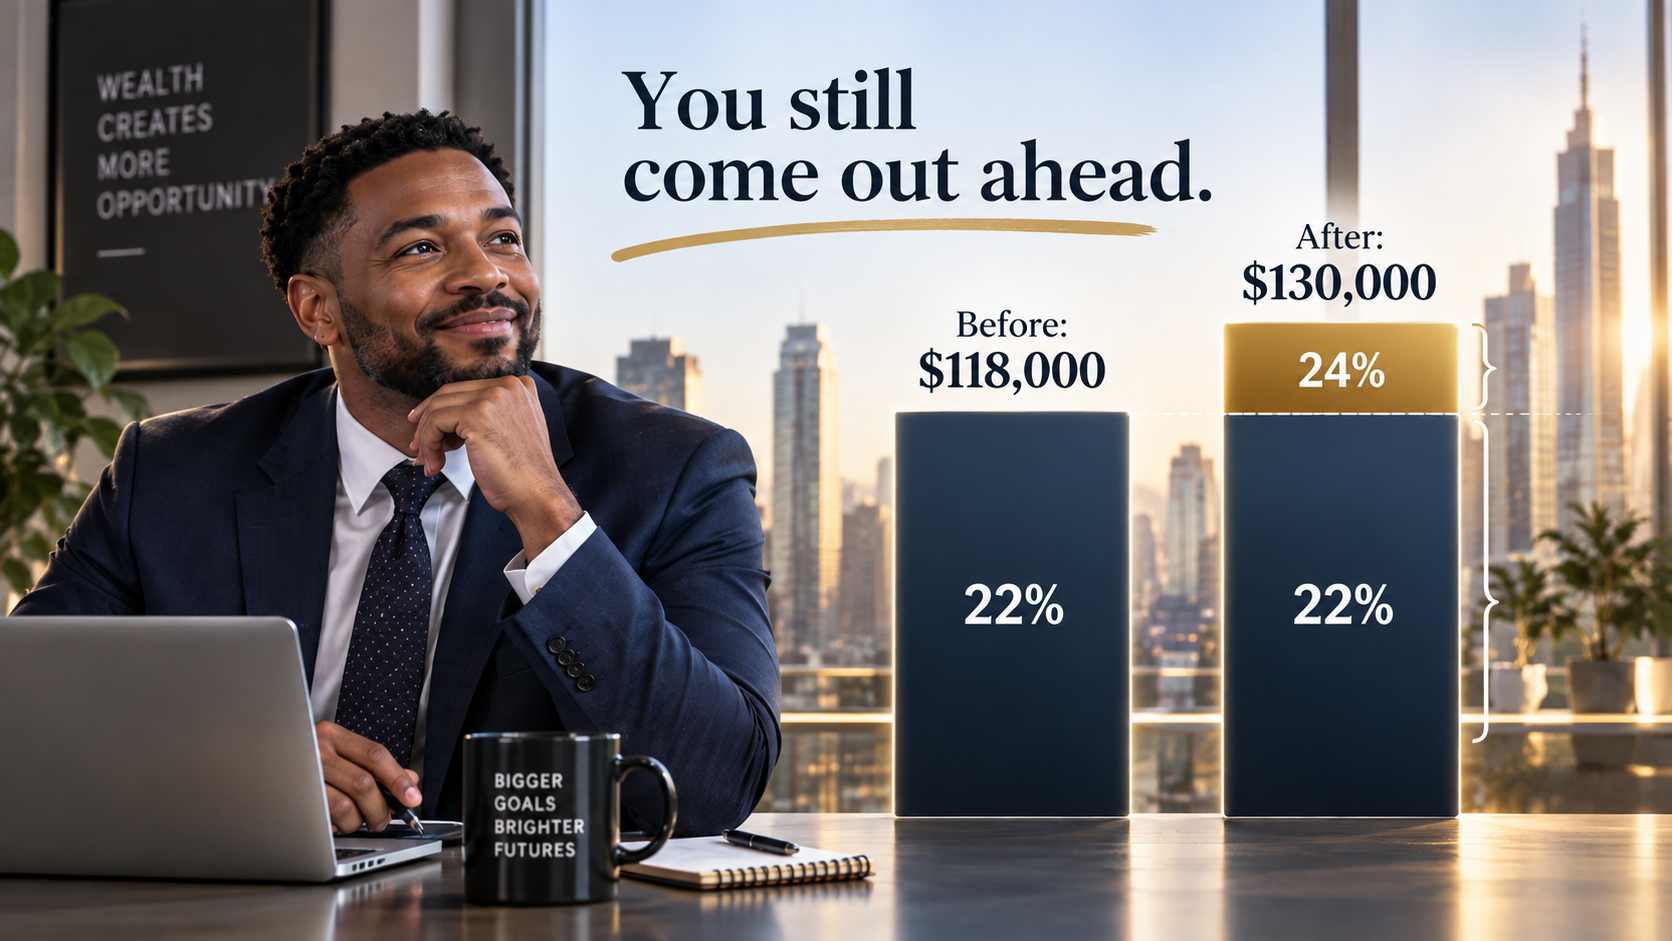
| Before | After | |
|---|---|---|
| Salary | $118,000 | $130,000 |
| Taxable income | $101,900 | $113,900 |
| Marginal bracket | 22% | 24% |
| Total modeled federal tax | $26,157 | $29,879 |
| Estimated remaining income | $91,843 | $100,121 |
This worker crossed into the 24% bracket — and still kept $8,278 of a $12,000 raise, about 69% of it.
A HIGHER MARGINAL TAX BRACKET DOES NOT RETROACTIVELY TAX YOUR PREVIOUS INCOME AT THE HIGHER RATE.
Being honest about the whole picture: a raise can interact with other parts of your financial life beyond the bracket itself — tax credits that phase out, benefit eligibility, income-based programs, retirement contribution rules, education assistance, and other phaseouts. Those are real, and someone near a phaseout edge should look carefully. But the progressive bracket system itself will not make a raise leave you with less. That specific fear is unfounded.
Six Figures Does Not Automatically Mean Rich
Here is the part that surprises people who finally get there.
| Salary | Estimated remaining after modeled federal tax | Per month |
|---|---|---|
| $35,000 | $30,303 | $2,525 |
| $50,000 | $42,355 | $3,530 |
| $75,000 | $61,593 | $5,133 |
| $100,000 | $79,180 | $6,598 |
Those monthly figures look transformative on paper. And then life expands to meet them.
A bigger apartment or a first house. A nicer car with a bigger payment. Higher insurance. More dining out. Travel. Subscriptions that quietly multiply. Better clothes. Social expectations that come with a new job title. Childcare. Tuition. And in most of the country, housing that costs considerably more than it did five years ago.
This is called lifestyle inflation — and it is the reason a person can triple their income over a decade and feel exactly as financially stretched as they did at the start.
Income can rise while financial security barely moves, if spending rises just as fast.
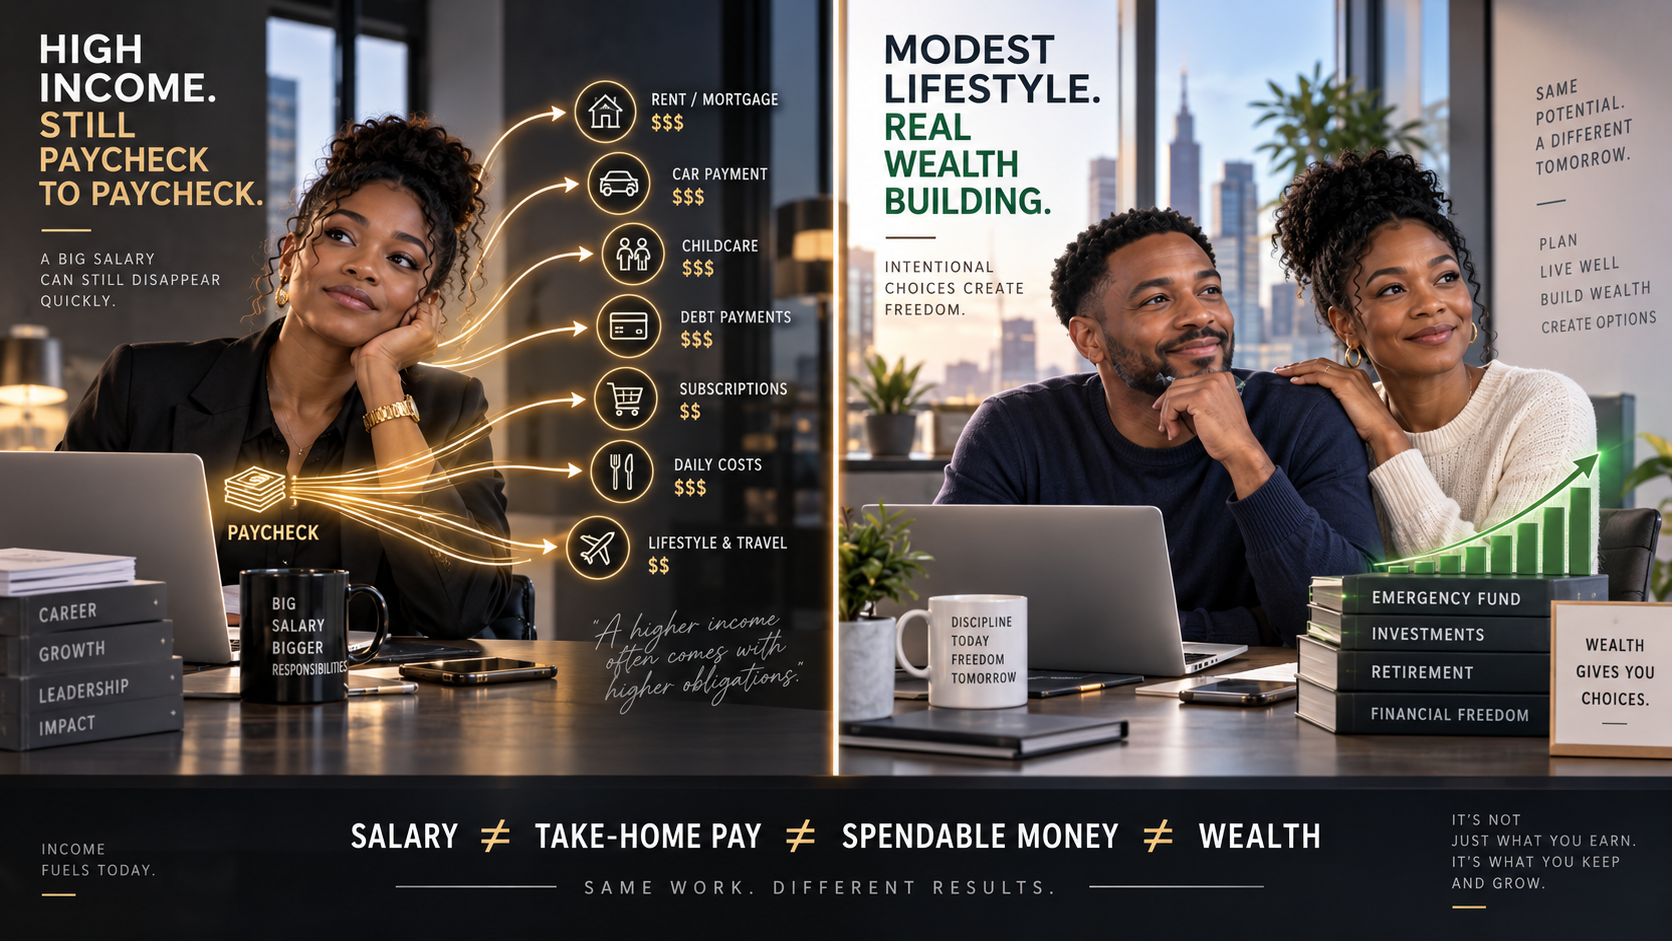
Four Different Money Numbers
Most people track one number. Financially literate people track four.
| Number | What it actually is |
|---|---|
| 1. Salary | What your employer agrees to pay before deductions. The number on the offer letter. |
| 2. Take-home pay | What reaches your account after payroll deductions. Always smaller. |
| 3. Spendable money | What is left after necessary obligations: housing, food, transport, insurance, minimum debt payments. |
| 4. Net worth | Everything you own minus everything you owe. The one that measures whether you are building something. |
Careful terminology note: economists use “disposable income” in a more specific technical sense than everyday speech does, which is why we avoid that term for number three.
INCOME IS NOT WEALTH.
A person can earn $200,000 a year and have almost no wealth — high spending, high debt, nothing accumulating. Another person earning substantially less can gradually build real wealth through disciplined saving, investing, debt management, and asset ownership over time.
That is not a moral judgment about either person. Circumstances differ enormously — medical costs, family obligations, where you live, what you inherited or didn't, what you were taught or weren't. The point is narrower and more useful: the size of your paycheck and the size of your net worth are two different measurements, and only one of them is what you keep.
What Should Grow Alongside Your Salary
As income increases, the financial questions change. This is a general progression, not a prescription — no single financial path is right for everyone, and yours will depend on your circumstances.
| Income stage | What tends to matter here |
|---|---|
| First job | Checking account. Savings account. Reading your paycheck. A basic budget. Avoiding unnecessary debt. Learning how credit works before you need it. |
| $30K–$50K | An emergency fund. Your employer's retirement plan and whether there is a match. Health insurance decisions. Responsible credit use. |
| $50K–$75K | Increasing retirement contributions. Reducing high-interest debt. Investment education. Deliberate career development. Reviewing insurance. |
| $75K–$100K | More deliberate tax planning. Larger cash reserves where appropriate. A retirement strategy. Homeownership planning if you want that. Diversification. |
| $100K+ | Reviewing withholding regularly. Retirement contribution strategy. Tax planning. Investment planning. Insurance review. Estate-planning awareness. Professional help when complexity justifies it. |
If credit is the piece you feel least sure about, fix that early. Our Zero to 850 series covers what credit is, what gets recorded, what interest actually costs you, and how to protect your identity. You should not have to ruin your credit to learn how credit works.
The Money You Never See on Your Stub
A worker focused only on salary can miss a substantial part of what a job actually pays. Consider total compensation:
- Salary
- Employer retirement plan match
- The employer's share of your health insurance premium
- Paid leave
- Bonuses
- Stock or equity compensation
- Education assistance
- Other benefits
An employer retirement match is the clearest example. If an employer matches a percentage of what you contribute to a retirement plan and you contribute nothing, you have left that match on the table entirely. It is compensation you were offered and did not take.
A $100,000 SALARY OFFER AND A $100,000 TOTAL-COMPENSATION PACKAGE ARE NOT THE SAME THING.
When you compare two job offers, compare the whole package.
If You Work for Yourself, the Math Changes
Some readers will earn money through freelancing, contract work, business ownership, creative work, consulting, or gig platforms. Dancers, choreographers, photographers, and teaching artists are very often in this category — sometimes with employee income and self-employment income in the same year.
Taxes work differently there, and the difference is not small. An employee pays 6.2% Social Security and 1.45% Medicare, and the employer pays a matching 6.2% and 1.45%. A self-employed person generally pays both halves. The self-employment tax rate is 15.3% — 12.4% for Social Security up to the same $184,500 wage base, and 2.9% for Medicare with no cap.
| Employee | Self-employed | |
|---|---|---|
| Basis | $100,000 wages | $92,350 net earnings (92.35%) |
| Social Security | $6,200 | $11,451 |
| Medicare | $1,450 | $2,678 |
| Total | $7,650 | $14,130 |
That is roughly $6,480 more. There are offsets — you can deduct the employer-equivalent half (about $7,065) when figuring your adjusted gross income, and legitimate business expenses reduce your net earnings before the tax is calculated at all. This comparison ignores both, plus the qualified business income deduction. It is an illustration of the structural difference, not a substitute for Schedule SE.
Self-employed people also generally handle things employees never think about:
- Estimated tax payments. You generally must make them if you expect to owe at least $1,000 in tax after subtracting withholding and refundable credits.
- Self-employment tax filing. Required once net earnings from self-employment reach $400.
- Business expense tracking and recordkeeping.
- Different retirement plan options.
- A more complex return.
DO NOT ASSUME THE EMPLOYEE FICA MATH IN THIS ARTICLE APPLIES TO SELF-EMPLOYMENT INCOME. IT DOES NOT.
And Then There's Your State
Everything above is federal only. Depending on where you live and work, you may also encounter state income tax, local or city income and wage tax, property tax, sales tax, and other state and local taxes.
Some states have no income tax at all. Others have rates that meaningfully change the picture. Some cities layer their own tax on top of the state's.
This is why we have not built a single “American take-home pay” number anywhere in this article. There isn't one. Two people with identical $100,000 salaries in two different states can end the year thousands of dollars apart, and neither of them did anything different at work.
Myth vs. Reality
MYTH
“If I enter the 22% bracket, the government takes 22% of everything I earned.”
REALITY
Only the taxable dollars that fall inside that bracket are taxed at 22%. At $100,000 single, the actual federal income tax was $13,170 — not $22,000.
MYTH
“A tax refund means the government gave me free money.”
REALITY
Usually it means more was withheld from your own paychecks than your final liability required. Refundable credits can also create or increase a refund.
MYTH
“If I make $100,000, I take home $100,000.”
REALITY
Federal income tax, payroll taxes, and other deductions all reduce what reaches you — before state and local taxes even enter the picture.
MYTH
“If I earn more money, I could lose everything to taxes.”
REALITY
The federal system applies increasing rates to portions of taxable income, never one rate to your whole salary. In our bracket-crossing example, a worker kept 69% of a raise that moved them into a higher bracket.
MYTH
“Everyone making the same salary pays the same federal income tax.”
REALITY
Three households at $100,000 in this article paid $13,170, $7,388 and $7,640.
When Should Someone Get Professional Help?
Not everyone needs a professional. As complexity grows, the value of one does too. The main categories:
| Professional | What they do |
|---|---|
| Tax preparer | Helps prepare tax returns. |
| CPA | May provide accounting, tax and other financial services depending on qualifications and engagement. |
| Enrolled Agent | A federally authorized tax practitioner who may represent taxpayers before the IRS within applicable rules. |
| Financial planner | Can help with broader financial planning depending on qualifications and services offered. |
| Investment adviser | Provides investment advice under applicable regulatory frameworks. |
| Attorney | May help with legal, estate, business or complex tax matters depending on specialty. |
Always verify credentials before hiring anyone. Ask what they are licensed to do, who regulates them, and how they are paid.
Official Resources
Go to the source. These are free, authoritative, and updated by the agencies themselves.
WHERE TO VERIFY EVERYTHING IN THIS ARTICLE
Internal Revenue Service — irs.gov — federal tax brackets, standard deductions, tax credits, Form W-4, the Tax Withholding Estimator, and self-employment information.
U.S. Department of Labor — dol.gov — federal and state minimum wage information, overtime rules, youth employment standards, and worker rights.
Bureau of Labor Statistics — bls.gov — occupational wage and employment data by occupation, state and metropolitan area. If you want to know what your intended career actually pays where you live, this is the place.
Social Security Administration — ssa.gov — Social Security wage base, benefit information, and your personal earnings record.
Frequently Asked Questions
Does entering a higher tax bracket mean all my income is taxed at that rate?
No. Only the dollars that fall within that bracket are taxed at that bracket's rate. Income below it continues to be taxed at the lower rates. This is what “progressive” means.
What is the difference between marginal and effective tax rate?
Your marginal rate is the rate on your next taxable dollar. Your effective rate is your total tax divided by an income measure — and you should always ask whether that measure is gross income or taxable income, because the two produce different percentages.
How much federal tax does a single person pay on a $100,000 salary in 2026?
Using the standard deduction and no other adjustments, taxable income is $83,900 and federal income tax is $13,170, plus $7,650 in employee Social Security and Medicare — $20,820 total, leaving roughly $79,180 before state and local taxes and other deductions.
Why is my paycheck smaller than my salary divided by the number of pay periods?
Because federal income tax withholding, Social Security, Medicare, and often state and local taxes, health insurance premiums and retirement contributions come out before you are paid.
Do I pay Social Security and Medicare on all my income?
Medicare applies to all covered wages with no cap. Social Security applies only up to the annual wage base, which is $184,500 for 2026. An Additional Medicare Tax of 0.9% applies above $200,000 ($250,000 for joint filers).
Is the federal minimum wage $7.25 everywhere?
No. $7.25 is the federal floor. Many states and cities set higher minimums, and where both apply, the worker is generally entitled to the higher one.
Why did I owe money at tax time even though taxes came out of every paycheck?
Withholding is an estimate. If less was withheld than your final liability required — because of a second job, a spouse's income, bonus income or side income — the difference is settled on your return.
Does having a child guarantee me the Child Tax Credit?
No. The child must meet age, relationship, residency, support and dependent tests, and Social Security number requirements apply to both you and the child. Income phaseouts also apply.
Back to That First Paycheck
There is nothing wrong with starting at minimum wage.
There is nothing wrong with wanting more, either.
Your first job may teach you how to arrive on time, follow instructions, work alongside people you did not choose, and earn your own money. Your next job may teach you a skill. The one after that may become a career. And one day the person staring at that first pay stub in a break room could be negotiating a six-figure salary, running a business, or signing other people's paychecks.
But as your income grows, your financial knowledge has to grow with it.
Learn the difference between gross pay and take-home pay. Understand what comes out of your check and why. Understand how tax brackets actually work — and never let anyone convince you that a raise will cost you money. Check your withholding when your life changes. Learn what deductions and credits you actually qualify for. Save before lifestyle expansion consumes every raise you ever get.
And when you finally reach the six-figure salary you once dreamed about, don't only celebrate the number printed on your offer letter.
Understand what that number means.
BECAUSE EARNING MORE MONEY IS AN ACCOMPLISHMENT. UNDERSTANDING WHAT TO DO WITH IT IS FINANCIAL POWER.
KEEP EXPLORING
Dance Mogul Magazine builds financial literacy the same way we build everything else — from lived experience, for people who were never handed the instructions. Start with Zero to 850 for credit, work through our empowerment workbooks for goal-setting and family conversations, explore the Dance Knowledge Hub for career and industry guides, and browse everything we have published in the Article Library.
EDUCATIONAL NOTICE
This article is intended for general financial education and does not constitute individualized tax, legal, investment or financial advice. Tax laws and individual circumstances vary and can change.
All figures reflect tax year 2026 federal rules as published by the IRS, SSA and DOL, verified as of September 2026. Every calculation shown was computed and independently re-verified by a second method before publication.
Readers should verify current information with the IRS and other appropriate government agencies and consult a qualified professional when advice specific to their circumstances is needed.
Sources: IRS Revenue Procedure 2025-32 (2026 inflation-adjusted items — rate schedules, standard deduction, Child Tax Credit, Earned Income Credit) · IRS IR-2025-103 · IRS Topic No. 560, Additional Medicare Tax · IRS, Child Tax Credit · IRS, Self-employment tax · IRS, Estimated taxes · IRS Publication 501 (Head of Household rules) · Social Security Administration, 2026 Social Security Changes · U.S. Department of Labor, Wage and Hour Division, Minimum Wage and Fact Sheet #32 Youth Minimum Wage · U.S. Bureau of Labor Statistics, Occupational Employment and Wage Statistics, May 2025. All figures verified September 2026.
Financial LiteracyTax Brackets 2026Take-Home PayMinimum WageSix FiguresMarginal Tax RateEffective Tax RateFirst PaycheckMoney ManagementSelf-EmpowermentYouth EmploymentCareer Growth
© 2026 Dance Mogul Magazine LLC | dancemogul.com | Inspiring Self-Empowerment Through Dance Culture